Safety

WORK COMP INSIGHTS
HELPING YOU UNDERSTAND. HELPING YOU STAY PREPARED.
Turning Claim Information into Better Outcomes
In today’s litigious environment, claims against industrial companies are inevitable, and off-the-shelf solutions to manage liability risks are too often inadequate.
In the high-risk manufacturing sector, where large-dollar claims are common, small to middle-market companies struggle to find experienced partners capable of providing targeted risk control and effective techniques to lower loss results and reduce the effect on the total cost of risk.
Here are four tactics industrial companies can implement to reduce the cost of claims.
The percentages, savings, and case examples below are historical material attributed in the supplied document to Property & Casualty 360, Randy Crawford, April 14, 2016. They are not guaranteed results or representations of The Holt Group’s client outcomes.
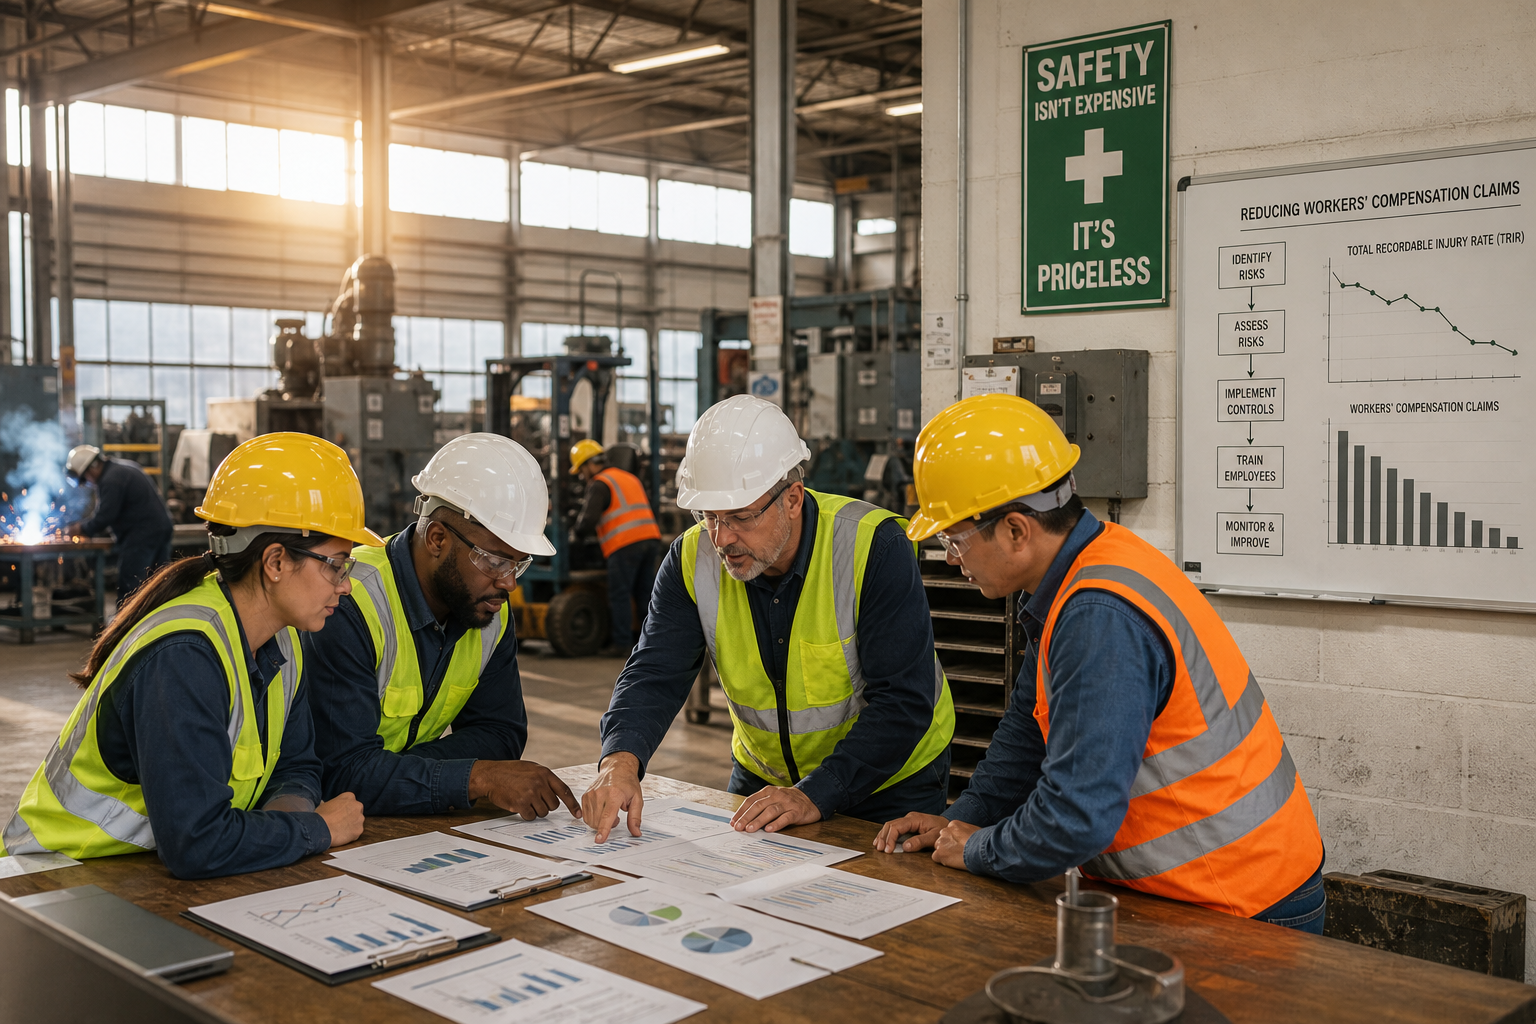
Effective claims management begins with an understanding of what has happened in the past followed by corrective actions to address trends in losses and improve financial outcomes. For casualty lines of coverage, this process should involve:
This process of improving safety in targeted areas can help reduce insurance premiums by up to 15 percent in the first 12 months.
Case in Point: A manufacturer and installer of equipment for large industrial projects could not improve its Workers’ Compensation experience because of increased injuries from inexperienced workers. This was preventing the company from qualifying for new projects.
The company had its Workers’ Compensation claim results analyzed and then isolated the activities and jobs that were creating the most claims. Following that, a targeted safety program that addressed the specific causes of those claims was designed and implemented.
This effort reduced the company's annual claims by more than $1.25 million in the first year and led to premium savings of $386,000. Additionally, the improved results allowed the company to bid on and win two large contracts worth more than $10 million.
The best way to keep claims costs low is to get them closed quickly. To help accomplish this, companies should conduct a claim review in person with insurance carrier claim adjusters to determine whether:
This has proven to be particularly effective at reducing the outstanding open claim amounts which, in turn, improves premium pricing. Quarterly claim reviews, such as the one described, can result in an annualized reduction in claims of 20%.
Case in Point: A manufacturer of high-end leather furniture achieved significant benefits as a result of the claims review. The company, which has a sophisticated manufacturing assembly line process and 300 team members, had experienced several consecutive years of frequent and severe worker injuries. Adding insult to injury, several of the claims had remained open for years without the manufacturer knowing why or how decisions were being made.
Upon conducting an analysis, it was determined quickly that claim reporting delays were common, no formal reporting or tracking process existed, and there was a lack of accountability within leadership. As a result, the company established a quarterly and ongoing claims review process, which included closing open claims at least six months prior to renewal. This effort reduced total claim reserves by $85,000 and a renewal premium the first year by $51,000.
Workers’ Compensation experience modification ratings (EMR) are complex formulas but understanding the way they are calculated can go a long way in helping to keep workers’ comp premiums in check.
To help manage Workers’ Compensation claims more efficiently, manufacturers should routinely evaluate the experience modifier the same way that regulators do to determine its accuracy and to forecast its future financial impact on premium.
Inaccurate EMR calculations are typically the result of errors in payroll amounts, inaccurate job classifications, improper claim reserves, and open claims that should be closed.
Case in Point: A large service provider that performs work on both public and private projects was struggling to qualify for new contracts because of its high EMR of 1.16. A review of the company’s open claim reserves identified many excessive claims that needed to be negotiated down.
Following negotiations with the insurer, the company was able to lower its excessive claims, which accounted for nearly 20% of the experience modification calculation. The improved reserves were reported to the National Council on Compensation Insurance, resulting in a reduction in the company’s EMR from 1.16 to 0.94.
Subsequently, the company was able to bid on and win several new contracts worth more than $15 million and also realized a premium savings of $264,000 over a three-year period.
KEY IDEA
Better Workers’ Compensation results don’t happen by accident.
Understanding where injuries are occurring, actively managing open claims, monitoring their financial impact, and taking steps to prevent future injuries can help an organization improve both claim outcomes and the long-term cost of risk.
Preventing Workers’ Compensation claims from occurring is highly correlated to the quality and scope of a company’s hiring practices. Loss control representatives and claims advocates can provide the framework for a screening procedure whereby medical providers evaluate candidates’ physical abilities based on detailed job descriptions.
Screening must comply with the ADA and applicable state law. Employers may ask applicants whether and how they can perform job duties, but may not require medical examinations or disability-related inquiries before a job offer. Post-offer medical examinations must apply to all entering workers in the same job category, and medical records must remain confidential. Consult legal counsel before implementing screening or making employment decisions.
Case in Point: A custom woodworking company that makes cabinets and doors developed an extensive pre-employment screening process, reducing team member injuries by 25%. Prior to putting the screening procedure in place, the business incurred several team member injuries, thereby driving an increase in its workers’ compensation premium.
The solution included reviewing the company’s existing hiring practices and identifying several areas to improve the screening process and reduce post-hire claims. Eventually, enhanced screening led to a reduction in both the EMR and OSHA [Occupational Safety and Health Administration] Frequency and Severity Rates. The company achieved premium savings of $68,500 over the first two years.
This recommendation and the others cited are only a few examples of how employing smart risk management strategies can help to mitigate the financial effect of adverse loss trends, lead to better managed claims and increase your overall competitive edge in the industry.
Property & Casualty 360
Randy Crawford, April 14, 2016
THE HOLT GROUP | Here to Help | www.theholtgroupllc.com
This Work Comp Insights is not intended to be exhaustive, nor should any discussion or opinion be construed as legal advice. Readers should contact legal counsel for appropriate advice. © Zywave, Inc., The Holt Group LLC All rights reserved. All images are from Google Images and Story Blocks. Revised 2026